Historical report: ChainCatcher published its analysis on November 15, 2026, at 15:07 China time. The prices and market readings below belong to that reporting period, not the present day.
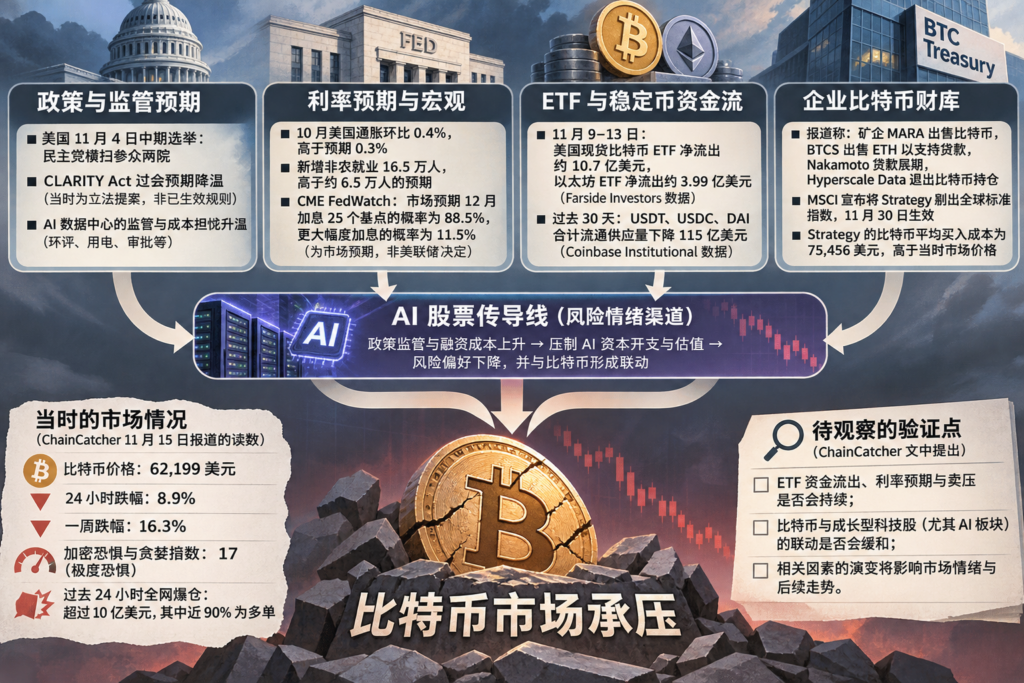
ChainCatcher reported that Bitcoin fell to $62,199 in the early hours of November 15, down 8.9% over 24 hours and 16.3% over a week. It described the move as the result of overlapping political, interest-rate, fund-flow and corporate-treasury pressures—not a selloff with one identifiable trigger. That is the article’s explanation, rather than a demonstrated breakdown of what caused each dollar of the decline.
The reported damage extended beyond spot prices. ChainCatcher put the crypto fear-and-greed index at 17, described more than $1 billion in liquidations over 24 hours, and said nearly 90% of those liquidations were long positions. Those figures help show why leverage matters here; an “extreme fear” reading, by itself, does not establish a market bottom.
Where the four-pressure argument rests
Politics and regulation. ChainCatcher linked the decline to the November 4 U.S. midterm election result, which it described as a Democratic sweep of both chambers of Congress. It argued that the result weakened expectations for passage of the proposed CLARITY Act and raised concerns about oversight and costs for AI data centers. The bill was a prospect in this account, not an enacted rule; the claimed effect on prices is an interpretation.
Interest rates and AI stocks. The article cited October U.S. inflation of 0.4% month over month, against an expected 0.3%, and 165,000 new nonfarm jobs, against an expectation of about 65,000. It also attributed to CME FedWatch an 88.5% market-implied probability of a 25-basis-point December rate increase and an 11.5% probability of a larger one. These were reported expectations, not a Federal Reserve decision. ChainCatcher’s argument was that higher financing costs could weigh on both leveraged Bitcoin positions and capital-intensive AI investments, making a technology-stock selloff a possible transmission channel rather than a separate story.
Fund flows. Citing Farside Investors, ChainCatcher reported roughly $1.07 billion in net outflows from U.S. spot Bitcoin ETFs over the five trading days from November 9 to 13, alongside about $399 million from Ether ETFs. It also cited Coinbase Institutional for an $11.5 billion decline over 30 days in the combined circulating supply of USDT, USDC and DAI. The article treated these as signs of weaker buying capacity; the figures alone do not identify why individual investors moved funds.
Corporate treasuries. ChainCatcher cited reported Bitcoin sales by miner MARA, an ETH sale by BTCS to support a loan position, a loan extension by Nakamoto, and Hyperscale Data’s exit from its Bitcoin holdings. It further said MSCI had announced Strategy’s removal from global standard indexes, effective November 30, and placed Strategy’s average Bitcoin purchase cost at $75,456—above the reported market price. The broader claim is a risk scenario: companies that once financed purchases through their shares might become sellers as financing conditions tighten. It does not establish that every treasury holder was selling.
The unresolved test in ChainCatcher’s account was whether ETF outflows, rate expectations and selling pressure would persist, and whether Bitcoin’s reported link with growth-oriented technology stocks would ease. For a speculative market, the distinction matters: a plausible cross-market narrative can explain what traders fear without proving which pressure drove the price.
Source: chaincatcher.com (originally published 2026-11-15 15:07 UTC+8)