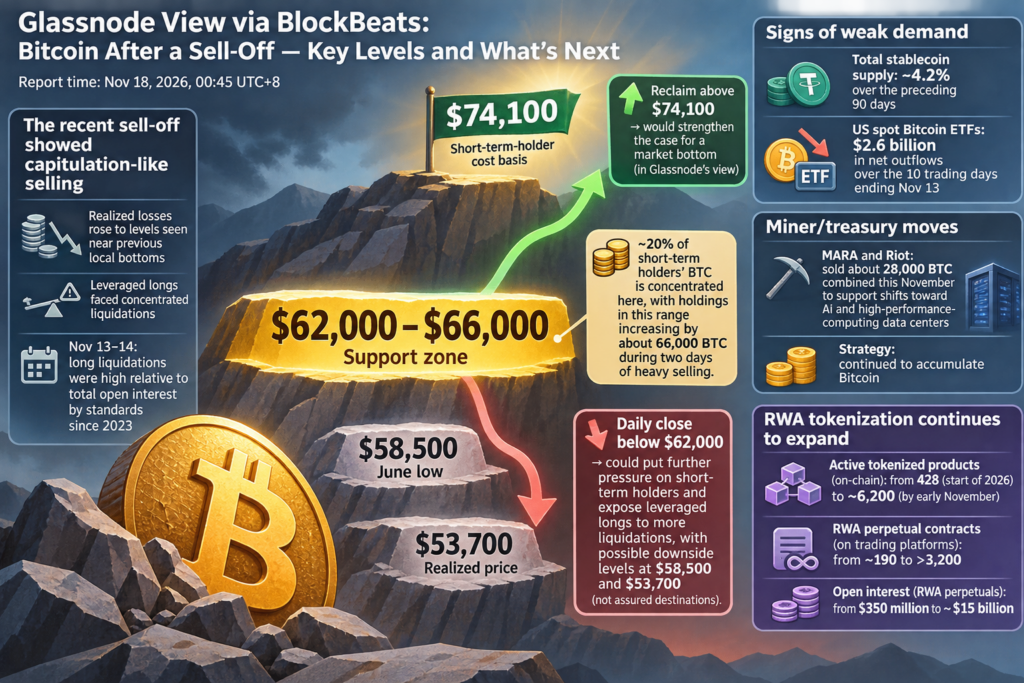
In a report published on November 18, 2026, at 00:45 UTC+8, BlockBeats summarized Glassnode’s view that a recent Bitcoin sell-off had produced capitulation-like selling. Glassnode said realized losses had risen to levels seen near previous local bottoms, while leveraged longs faced concentrated liquidations. Long liquidations on November 13–14 were high relative to total open interest by standards seen since 2023.
The levels in Glassnode’s assessment
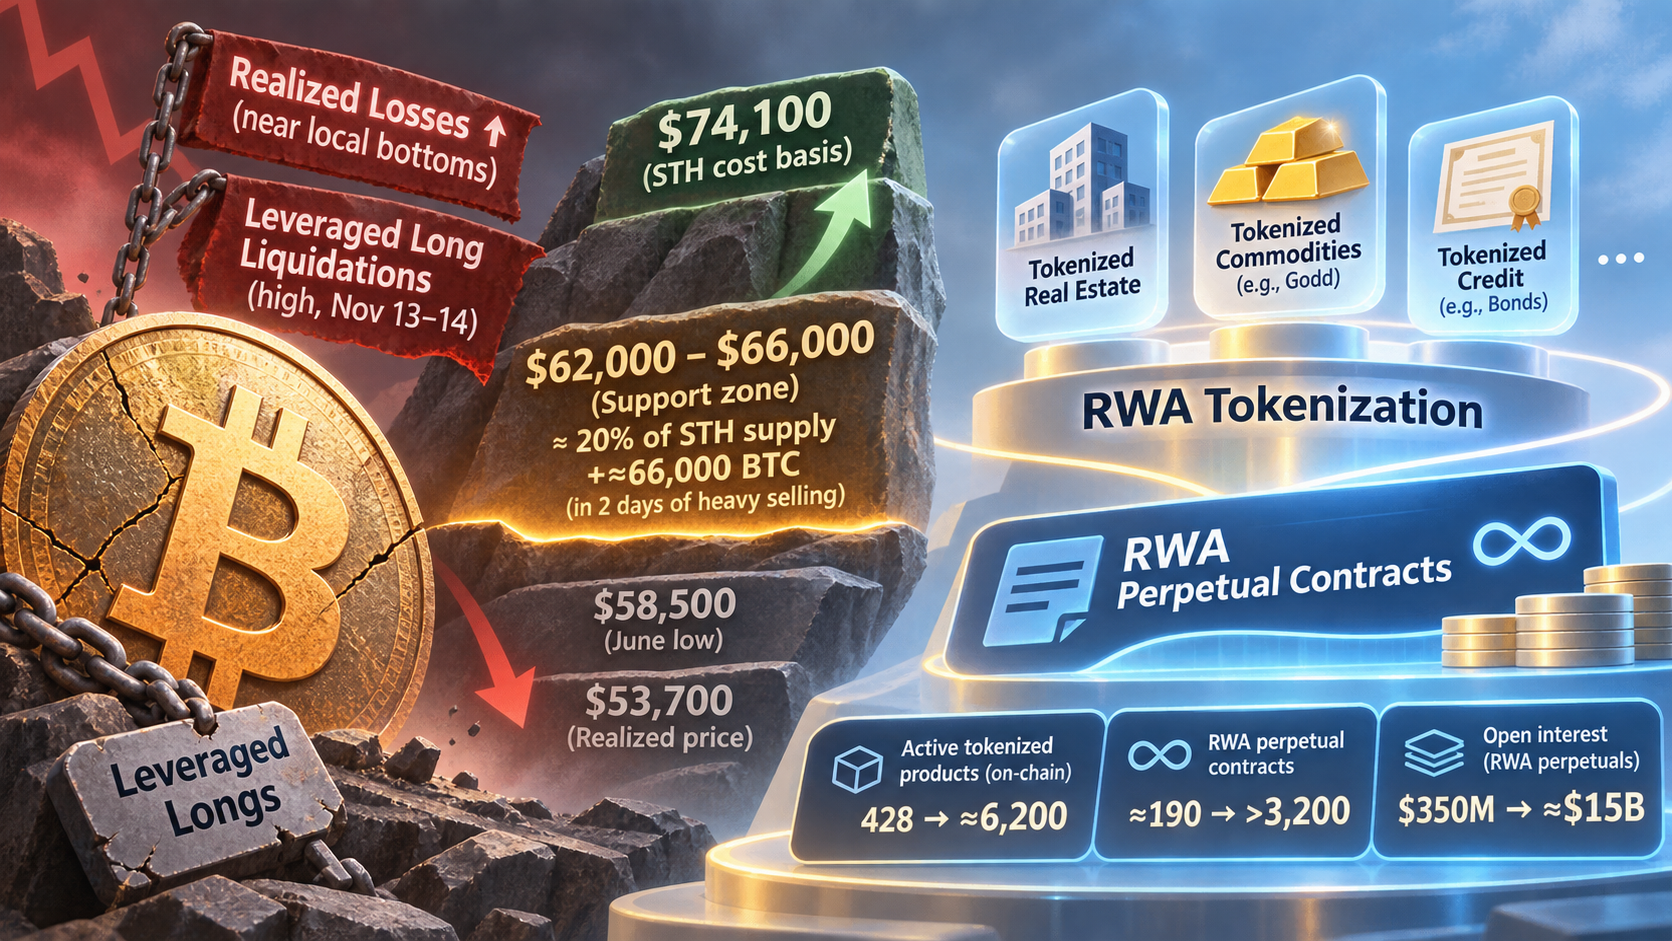
Glassnode identified $62,000–$66,000 as a support zone. It said roughly one-fifth of short-term holders’ Bitcoin was concentrated there, with holdings in that range increasing by about 66,000 BTC during two days of heavy selling. That concentration describes where coins changed hands; it does not establish that the level will hold.
The report also pointed to weak demand: total stablecoin supply had fallen 4.2% over the preceding 90 days, and US spot Bitcoin ETFs had recorded $2.6 billion in net outflows over the 10 trading days ending November 13. BlockBeats reported that MARA and Riot had sold about 28,000 BTC combined that November to support shifts toward AI and high-performance-computing data centers, while Strategy continued to accumulate Bitcoin.
In Glassnode’s conditional outlook, a daily close below $62,000 could put further pressure on short-term holders and expose leveraged longs to more liquidations. It cited $58,500, the June low, and $53,700, the realized price, as possible downside levels—not assured destinations. A move back above $74,100, the short-term-holder cost basis, would strengthen the case for a market bottom, in its view.
A separate RWA expansion
Despite the weak Bitcoin demand described in the report, BlockBeats said crypto’s real-world-asset tokenization activity had continued to expand. The number of active tokenized products on-chain rose from 428 at the start of 2026 to about 6,200 by early November. RWA perpetual contracts on trading platforms increased from roughly 190 to more than 3,200, while their open interest grew from $350 million to about $15 billion. Those are measures of activity and exposure, not evidence that Bitcoin demand has recovered.